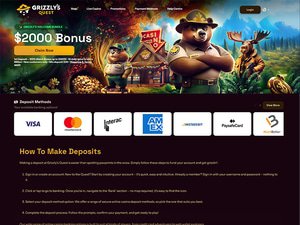
Choosing a casino banking method is less about finding the longest payment list and more about understanding which options fit your province, account currency, verification status and withdrawal plans. The grizzlys quest casino canada information available for Canadian users points to a banking area where options can differ by account and location. A practical comparison should therefore examine how each method works, what it may require and whether it supports both deposits and withdrawals.
Start with the cashier, not the payment brand
The first useful step is to open the casino’s Bank or Cashier area and record what is actually displayed for the account. Public descriptions mention Interac and Interac e-Transfer, Visa, Mastercard, Apple Pay, Google Pay and bank transfer. Some cashier configurations may also show INSTADEBIT, MuchBetter, Paysafecard or Flexepin. That list should be treated as indicative rather than guaranteed, because availability can depend on the player’s province, account review and current cashier configuration.
Look separately at deposit and withdrawal columns. A method that accepts funds may not support cashouts, and the presence of a familiar logo does not establish that it can be used in both directions. Before depositing, note the withdrawal route, minimum amount, identity requirements and any stated processing charge. Saving a screenshot of the displayed terms can also help you compare the information later if the cashier changes.
Currency is another basic usability question. Canadian accounts can use CAD, which avoids having to compare a displayed balance with a different currency in your personal bank account. However, CAD availability does not mean every payment method operates identically in Canadian dollars. Check the confirmation screen for the transaction currency, any conversion warning and the final amount before approving a payment.
Which options suit different payment priorities?
Interac and Interac e-Transfer may be attractive to users who already use Canadian online banking and prefer not to enter card details. Their suitability depends on the exact option shown in the cashier and whether it is enabled for withdrawals. Read the instructions carefully, especially where a payment must be sent from an account held in the same name as the casino account.
Visa and Mastercard can be convenient for deposits, while digital wallets and mobile payment services may offer an additional layer between the casino and a primary card. Convenience should not be confused with universal withdrawal access. A card, wallet or prepaid method may be deposit-only, or it may require separate proof that the account belongs to the player. The cashier’s current wording is more useful than a general assumption about how a payment brand normally works.
Bank transfer can make sense for larger withdrawals when the method is available, but it may involve more banking details and a longer processing window. Prepaid options such as Paysafecard or Flexepin may help with spending control, yet they commonly need to be checked for cashout compatibility before use. A sensible comparison asks three questions: how quickly can funds be credited, can the same route receive a payout, and what paperwork could be requested?
What changes when verification enters the process?
Banking choices are often affected by verification rather than by payment technology alone. The available material indicates that identification checks may occur before a first withdrawal or when the cashier requests further review. Possible documents include government-issued identification, a recent utility bill or bank statement showing the address, and evidence that the player owns the payment method.
Matching information is important. The name and personal details on the casino account should correspond with the identity and payment records supplied during review. A suitably masked payment-card image or wallet information may be requested to demonstrate ownership. Do not send documents through an unverified channel; use the secure account or the verification route identified by the operator’s own help or cashier instructions.
Verification can also affect timing. A payment may appear successful while a later withdrawal remains pending because the account or transaction needs review. This is one reason to avoid choosing a method solely because its deposit step looks instant. Before making a qualifying deposit, check whether the operator requires a completed wagering condition, payment ownership evidence or other account checks before a payout can be processed.
Compare costs, limits and processing windows carefully
Published descriptions give varying figures for ordinary minimum deposits and withdrawals, so readers should not treat one reported amount as a permanent rule. Some reports mention ordinary deposits as low as C$1 or C$10, while the current welcome-spin conditions require at least C$20 for each qualifying deposit. Those are different contexts. The amount shown in the live cashier and the applicable promotion terms should control the decision.
Withdrawal minimums and timeframes can vary just as widely. Reports describe possible electronic-method processing within roughly 24 hours, while bank transfers and some card payments may take several business days, sometimes up to seven. These figures do not guarantee a result for every account. Separate the operator’s internal processing time from the time a bank or payment provider takes to complete the transaction.
Fees deserve equal attention. The available material describes a possible requirement to wager deposited funds once before withdrawal, with reported charges of 10% for some methods or 15% for card deposits if funds are withdrawn without that condition being met. Because the reports are not uniform, read the current banking and account terms before acting. For general guidance on financial decisions and consumer concerns, consult the Financial Consumer Agency of Canada.
Use a simple decision process before depositing
A short checklist can make the banking page easier to evaluate. First, confirm that the account is eligible in the player’s province; the available material states that promotions are unavailable to Ontario residents and that local conditions can apply. Second, confirm that CAD is selected if that is the intended account currency. Third, identify at least one realistic withdrawal method before choosing a deposit method.
Next, compare the complete transaction path rather than the first step alone. Record the minimum deposit, minimum withdrawal, possible fee, expected processing stages and documents that may be requested. If a payment option is listed only as a deposit method, assume nothing about cashouts. When the cashier presents several routes, prioritise the one whose withdrawal instructions are clearest, even if another option appears more convenient for adding funds.
Finally, keep records of confirmations, transaction references and any support correspondence. If a payment remains pending, check the account’s banking history and current verification requests before submitting repeated transactions. Support channels such as the Help Centre, FAQ and live chat may clarify account-specific availability, but readers should rely on the answer provided for their own province and cashier rather than on an older review or a third-party payment list.
Questions Canadian users often ask
Can every listed payment method be used for withdrawals?
No. The available information distinguishes between payment methods shown in the cashier and methods that support cashouts. Some options may be deposit-only, while others may require identity or ownership checks first. Confirm the withdrawal route in the account’s current banking area before depositing, rather than relying on the payment brand alone.
Are the published minimums and processing times fixed?
No. Reported minimums and timeframes vary between cashier configurations and payment methods. The current account may show different requirements from an older review, and a bank or wallet can add its own delay. Treat displayed cashier terms as the relevant information and check for fees before confirming a transaction.
Why might a withdrawal need extra documents?
Identity and payment ownership reviews can be requested before a first withdrawal or when a transaction requires further checking. The operator may ask for identification, address evidence or proof that the payment method belongs to the account holder. Incomplete or mismatched information can delay processing until the review is resolved.